 Excavator
294 models
 Backhoe Loader
51 models
 Crane
68 models
 Concrete Mixer
79 models
 Wheel Loader
54 models
 Compactor / Roller
45 models
 Motor Grader
42 models
 Concrete Pump
66 models
 Skid Steer Loader
11 models
 Telehandler
13 models
 Dozer


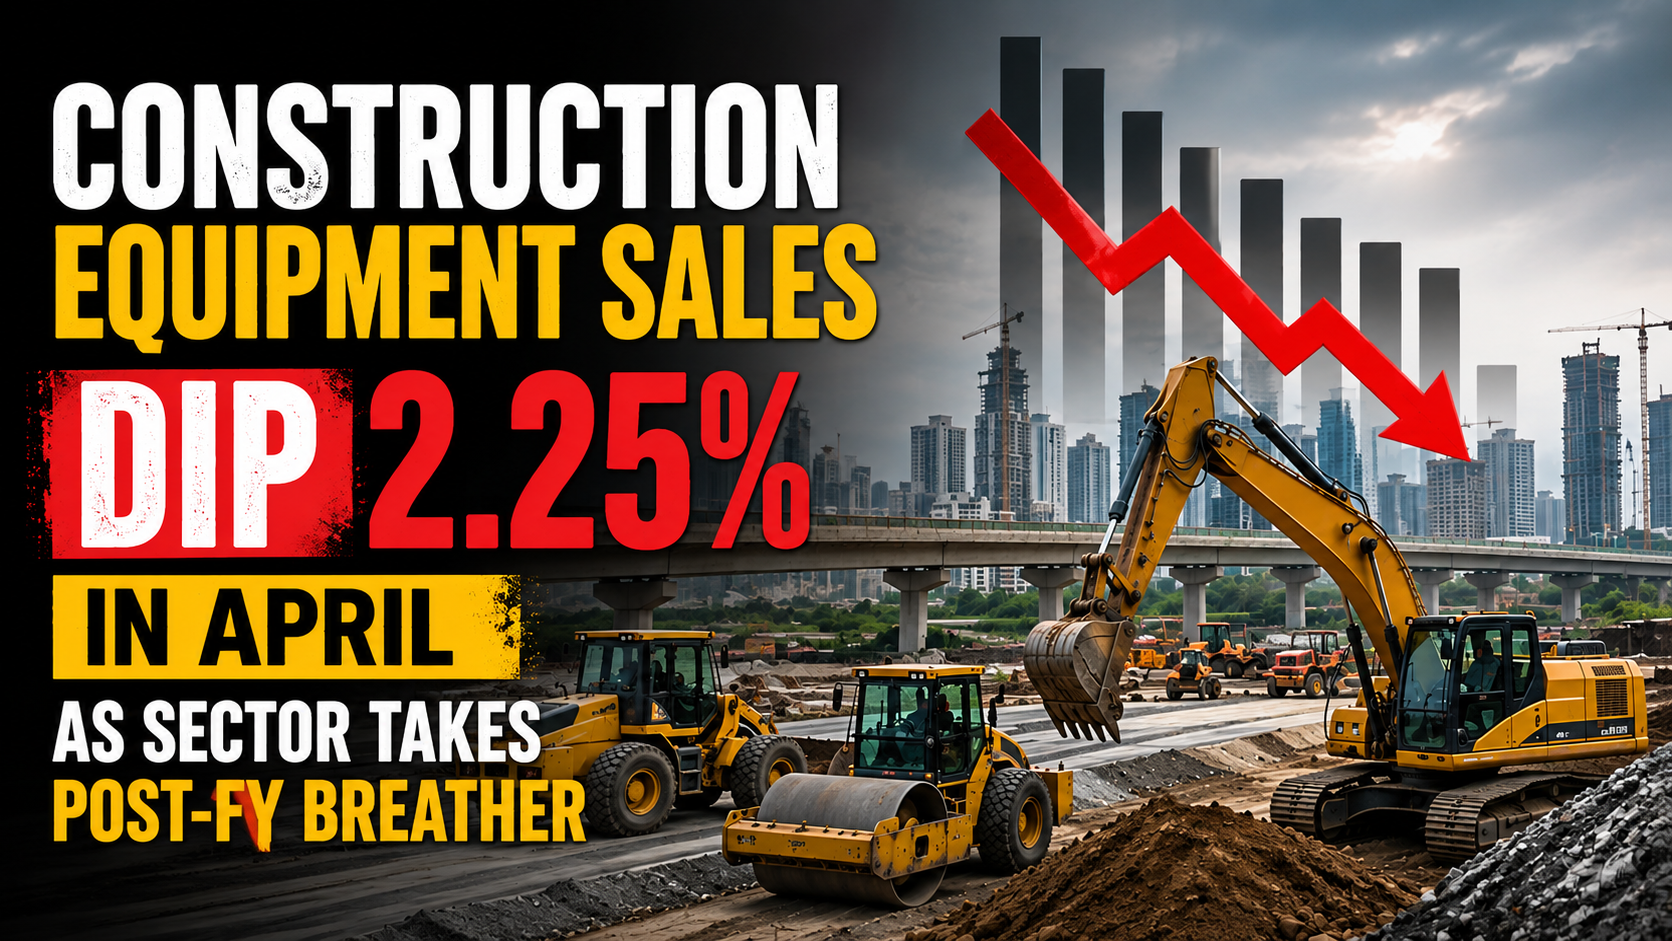
In short: Construction equipment sales April 2026 came in at 6,348 units, down 2.25% year on year and the only vehicle category to shrink in a record month for the wider auto industry, per FADA. JCB India took 45.02% share on 2,858 units; the top five makers now hold over 76% of the market. Rural sales grew 2.28% while urban fell 7.58%. Dealers read it as a post-financial-year pause, not a downturn.
Construction equipment sales April 2026: the headline numbers
New Delhi, May 5, 2026 – India’s construction equipment sector recorded a modest decline of 2.25% in April 2026, retailing 6,348 units compared to 6,494 units in April 2025, according to data released today by the Federation of Automobile Dealers Associations (FADA).
This made construction equipment the only vehicle category to post negative growth in a month when the overall automobile industry celebrated record-breaking sales across most segments.
JCB India Strengthens Market Leadership
Despite the overall market decline, JCB India Limited reinforced its dominant position by selling 2,858 units of its backhoe loader and excavator range and capturing a 45.02% market share—up from 41.18% a year ago. The British excavator and loader manufacturer showed a 6.9% year-on-year growth even as the broader market contracted.
Action Construction Equipment held second place with 733 units (11.55% share), though it witnessed a decline from 928 units last year. Ajax Engineering claimed third spot with 522 units (8.22% share), posting an impressive 14.2% year-on-year growth.
Escorts Kubota Limited’s Construction Equipment division sold 501 units (7.89% share), while Bull Machines rounded out the top five with 227 units (3.58% share), registering a strong 35.1% growth.
Other notable performers included Tata Hitachi Construction Machinery (216 units), Case New Holland (162 units), Caterpillar India (130 units), Schwing Stetter India (100 units), and Indo Farm Equipment (82 units). Mahindra & Mahindra’s construction equipment division contributed 76 units, while Liugong India sold 70 units.
The top five manufacturers now control over 76% of the market, indicating continued consolidation favoring established brands.
Urban-Rural Divide Emerges
The segment showed divergent trends across geographies. Urban markets, accounting for 43.4% of sales, declined 7.58% year-on-year, while rural markets grew 2.28%, supported by government infrastructure schemes and rural road construction projects.
Month-on-month, sales dropped 8.08% from March 2026’s 6,906 units—a typical post-financial-year correction as new procurement cycles begin.
What’s Behind the Slowdown?
Industry experts point to several factors: the natural reset after March’s year-end buying rush, elongated financing approval times, and concerns over IMD’s forecast of above-normal heatwaves that could slow construction activity.
“The decline reflects timing rather than fundamentals,” said Mr. Sai Giridhar, FADA Vice President. “Infrastructure capex remains robust, but April typically sees a pause as companies reset budgets and await new project approvals.”
Unlike other vehicle categories rapidly adopting alternative fuels—electric three-wheelers now command 60% market share—construction equipment remains 100% diesel-dependent, making it vulnerable to fuel price volatility linked to West Asian geopolitical developments.
Outlook Remains Cautiously Optimistic
FADA’s dealer survey shows 55.60% expect growth in May 2026, supported by the extended marriage season, new OEM scheme cycles, and sustained infrastructure demand. For the May-July quarter, 50.90% of dealers anticipate growth.
Notably, 36.46% of dealers have revised their full-year FY’27 expectations upward, suggesting confidence in the medium-term infrastructure story remains intact despite near-term headwinds.
The recovery will likely hinge on monsoon performance, government capex flow, pending project approvals — the kind of work the country’s largest EPC contractors put out to machine owners — and the potential replacement cycle for equipment purchased during the 2018-2020 infrastructure boom.
Top Construction Equipment Brands Performance (April 2026):
- JCB India: 2,858 units (45.02% share) ⬆️ +6.9%
- Action Construction: 733 units (11.55% share) ⬇️ -21.0%
- Ajax Engineering: 522 units (8.22% share) ⬆️ +14.2%
- Escorts Kubota CE: 501 units (7.89% share) ⬆️ +2.9%
- Bull Machines: 227 units (3.58% share) ⬆️ +35.1%
If a flat month is when you plan to buy, it is usually the better moment to negotiate: compare variants on the comparison pages, read our guide to negotiating a machine price, and work the funding out on the equipment finance page before you sign.
Retail figures are FADA vehicle-registration data for April 2026.
Monthly retail numbers, market shares and dealer sentiment are as published by the industry association for the month shown and are revised from time to time. Confirm the current figures with the official source or your dealer before acting on them.