 Excavator
313 models
 Backhoe Loader
51 models
 Crane
68 models
 Concrete Mixer
79 models
 Wheel Loader
54 models
 Compactor / Roller
45 models
 Motor Grader
42 models

 Concrete Pump
66 models
 Skid Steer Loader
11 models


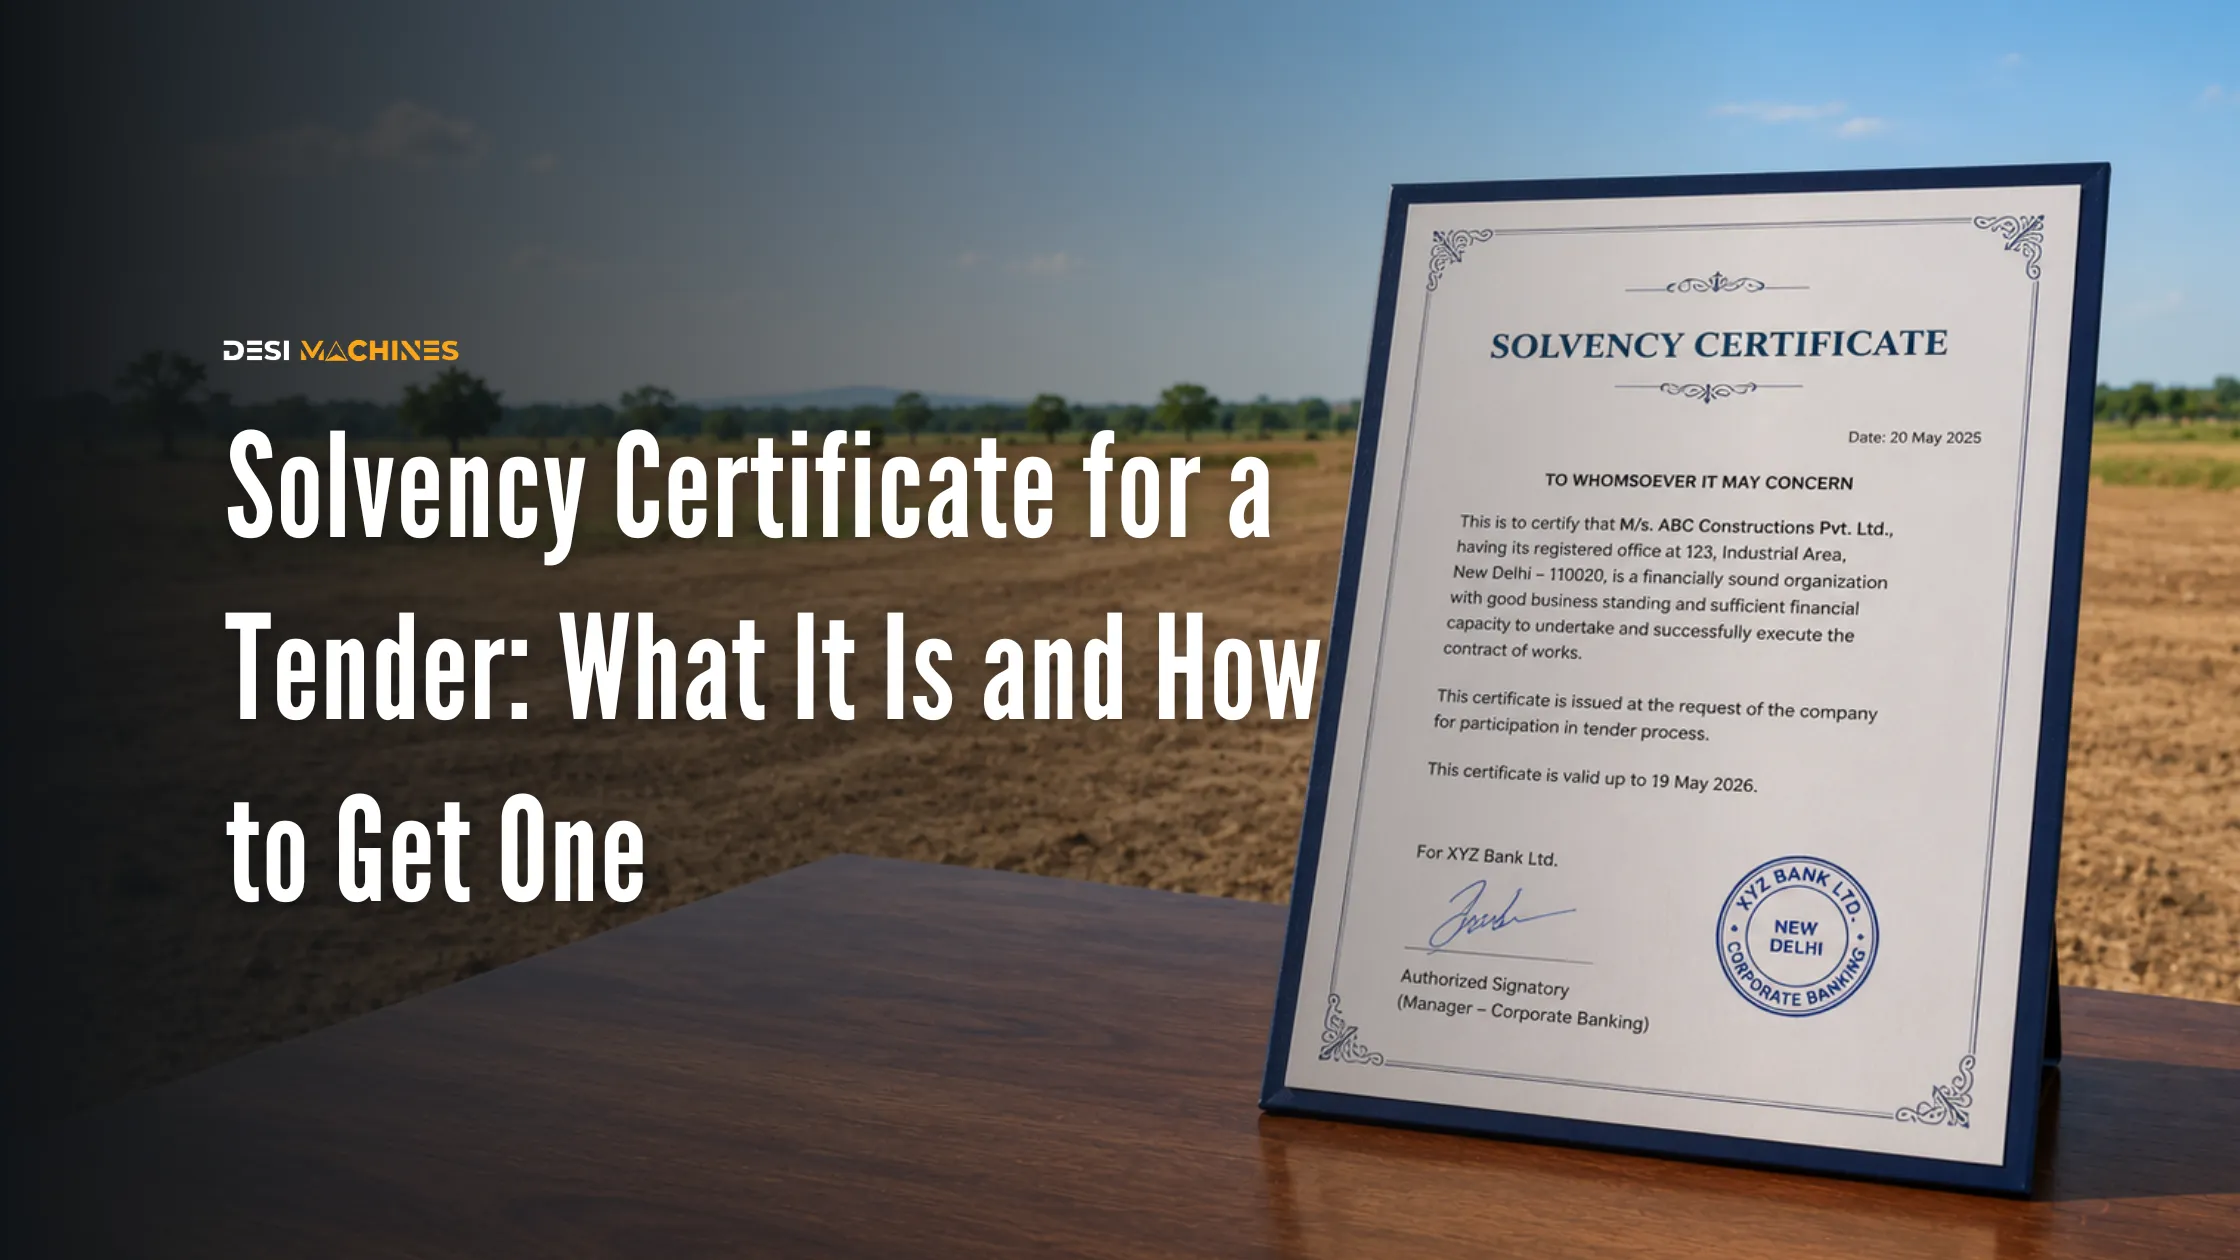
A solvency certificate for tender submission is a letter from your bank saying you are financially sound up to a stated amount on a stated date. It is also called a bank solvency certificate or a banker’s certificate of solvency. Departments ask for it to check you can fund mobilisation before the first running bill arrives. Your branch issues it, it commonly takes one to two weeks, it may cost you a lien on a deposit, and it carries a validity, so an expired certificate for the right value is rejected exactly like a missing one.
The first time a machine owner reads a tender document properly, one line usually stops him. Somewhere under eligibility sits a demand for a solvency certificate from a scheduled bank for a value tied to the estimated cost of the work. The bid closes in twelve days. The branch manager has never been asked for one before.
This is a document worth understanding well before you need it, because it is entirely a matter of lead time. Owners who keep a current certificate on file bid whenever work appears. Owners who do not, watch the tenders they could have won close without them.
What a solvency certificate for tender submission actually says
The certificate is short, often a single paragraph. The bank states that you have maintained an account with the branch for a period, that your dealings have been satisfactory, and that in the bank’s opinion you are solvent, good for a stated figure, as on a stated date.
Read what that does and does not mean. The bank is giving an opinion on your standing. It is not promising anyone any money. If you take the contract and fail, the department cannot recover a rupee under this certificate. That distinction matters because it explains why the certificate is comparatively easy to obtain and why departments ask for other instruments alongside it.
Why the tender asks for it at all
Government and public-sector work runs on a simple, uncomfortable rhythm: you mobilise, you work, you measure, you bill, and then you wait. The department knows this better than anyone. The solvency certificate is its rough filter for whether you can carry the site until money starts moving: machines to shift, diesel to buy, an operator’s wages, security, sometimes a month of work before a single bill is even raised.
That is why the required value is normally pegged to the estimated cost of the work rather than to your turnover. The department is sizing your ability to fund a gap, and the gap is real. How long that wait actually runs on Indian government and EPC work is set out in running bill cycle and contractor payment delay.
How to get one from your bank
The process is branch-level and unglamorous. Expect roughly this sequence.
Apply in writing at your own branch. The certificate comes from where your account and history sit, not from any branch of the bank. A relationship of a year or more makes this straightforward; a three-month-old account rarely does.
State the amount and the purpose. Name the figure the tender demands and say it is for tender submission. Vague requests come back for clarification and burn a week.
Give the branch what it will ask for anyway. Account details, business registration, your last set of filed returns and financial statements, and details of any facilities you already hold with the bank. If you have an equipment loan running, that file already contains most of it.
Expect a security conversation. Depending on the amount and your balances, the branch may be comfortable on the strength of your existing relationship, or may want a lien marked on a fixed deposit. Ask which, and how much will be blocked, before you apply.
Collect it on the bank’s letterhead, signed, dated and stamped. Check the spelling of your firm’s name against the tender registration exactly. A mismatch between the certificate and your bid registration is a rejection that has nothing to do with your money.
What it costs you, and the part owners miss
Banks charge a fee for issuing one, and the fee varies by bank, by amount and by your relationship, so ask your branch for its current schedule rather than working off a figure you read somewhere. The fee is rarely the real cost.
The real cost is the lien. If the branch marks a lien on a deposit to support the certificate, that money is out of reach for the period the lien runs. An owner who blocks a deposit to certify solvency for a contract, and then needs the same money to mobilise on that contract, has solved one problem by creating another. Settle the mobilisation funding question first, whether that is your own reserves, a working-capital limit, or borrowing against an asset you already own.
Keep the timing in mind too. Certificates carry a validity, and tenders usually want a recent one. Getting a certificate issued for a bid you then lose means paying again for the next bid a few months later. Owners who bid regularly plan for that as a running cost of the business, not a one-off.
Solvency certificate, EMD and bank guarantee are three different things
These get confused constantly, and mixing them up in front of a tender clerk is expensive. CPWD’s 2026 enlistment rules also accept a chartered accountant’s net worth certificate for a tender in place of the banker’s certificate, at under a third of the amount.
| Instrument | What it does | Does the bank pay out? |
|---|---|---|
| Solvency certificate | States the bank’s opinion that you are good for a stated amount | No |
| Earnest money deposit | Your own money lodged with the bid, refunded when the bid process ends | Not applicable; it is your cash |
| Bank guarantee | The bank’s written promise to pay the department if you default | Yes, on invocation |
Earnest money and the exemptions small enterprises can claim are covered in bidding for government construction tenders, and the deposit itself, from amount to refund, in EMD in tender. The guarantee is the instrument that genuinely puts the bank at risk, which is why it is secured, priced and approved quite differently from a solvency letter. Talk to your lender early if a tender asks for one. Comparing what different lenders will do for a machine-owning business is worth the afternoon, and a side-by-side look at bank and NBFC terms is a reasonable starting point.
The guarantee side of that comparison has its own cost, and it lands after you win rather than before. A performance bank guarantee carries a commission for every year it stays alive and blocks a margin at your bank until the contract is released, which is why a winning bid can still tighten your cash.
How much solvency, and for how long: one state’s rules in figures
Most tender documents leave the value to the clause, but registration rules sometimes print it. Maharashtra Jeevan Pradhikaran, the state’s water supply and sewerage authority, publishes its rules for registration of contractors with a solvency figure against every class of civil registration. The class decides the size of work you may take, and the solvency figure is what your bank has to certify to get you into that class. The guide to MJP contractor registration sets out the turnover, water supply experience and fees that go with each Maharashtra Jeevan Pradhikaran class.
| Civil class | Works up to (₹ lakh) | Solvency required (₹ lakh) |
|---|---|---|
| I | Without limit | 250 |
| I(a) | 2,000 | 200 |
| II | 750 | 75 |
| III | 300 | 30 |
| IV | 150 | 15 |
| IV(a) | 90 | 9 |
| V | 50 | 5 |
| VI | 15 | 2 |
| VII | 7 | 1 |
From class I(a) down to class V the solvency asked is exactly one-tenth of the work limit. The two smallest classes ask a little more than that, ₹2 lakh against ₹15 lakh and ₹1 lakh against ₹7 lakh, and the unlimited class I is set at ₹250 lakh.
The same rules answer the two questions most tender clauses leave open. The certificate has to be in the authority’s own proforma (its Annexure B) and is treated as valid for 12 months from the date of issue. A contractor from outside Maharashtra has to submit an original certificate from a nationalised scheduled bank located in the state. A labour co-operative society can give a certificate from the Registrar of the District Federation on its capacity and financial resources instead.
Other departments set their own figures, so read this as one worked example of a class-based clause, not a national rule. Solvency is usually one of two financial tests in the same clause; the other is turnover, and how departments compute it is in average annual turnover criteria in tender.
Why bids get rejected on this one document
Technical evaluation is mechanical. Four failures account for most of the damage.
Wrong value. The certificate is for less than the clause demands. Read the clause twice: some departments set it as a percentage of estimated cost, others as a flat figure by class of work.
Stale date. Issued outside the window the tender allows. A certificate from fourteen months ago is not a near miss; it is a rejection.
Name mismatch. Issued to the proprietor personally when the bid is in the firm’s name, or the other way round. Match the legal entity that is registered to bid.
Wrong issuer. A chartered accountant’s certificate where the clause specified a scheduled bank, or a co-operative bank where the clause said scheduled commercial. Departments do not treat these as equivalent.
None of these are financial failures. They are reading failures, and they cost the same as being broke.
Treat the solvency certificate as standing paperwork
Treat the solvency certificate as standing infrastructure for a bidding business rather than a document you chase per tender. Build the banking relationship, keep your returns and statements current, know what your branch will want and what it will block, and get the certificate issued before the tender you actually want appears. The owners who win departmental work are rarely the ones with the best machines. They are the ones whose paperwork was ready on the day.
Once the file is in order, the next steps are enlistment and finding the work. Start with PWD contractor registration and registering on the GeM portal, then watch live tenders and machine opportunities as they open. If the bid needs another machine on the ground, compare excavator models and prices and what equipment finance would cost against the contract.
Fees, validity periods, required values, lien practice and eligibility conditions are indicative, vary by bank, department, tender and date, and should always be confirmed with your bank branch and the tender document itself before you bid. DesiMachines is not liable for decisions taken on the basis of information that may have changed after publication.