 Excavator
294 models
 Backhoe Loader
51 models
 Crane
68 models
 Concrete Mixer
79 models
 Wheel Loader
54 models
 Compactor / Roller
45 models
 Motor Grader
42 models
 Dozer
41 models
 Concrete Pump
66 models
 Skid Steer Loader
11 models
 Telehandler
13 models


Ceramic and vitrified tiles carry a wastage allowance of 2.5 per cent in CPWD’s analysis of rates, steel bars 5 per cent, plywood and glass 10, and Kota stone 15. The Indian Standard on material quantities, IS 10067, leaves wastage out of its constants on purpose and says each department must assess it for itself.
So the honest answer to “what is the standard wastage of materials in construction” has two parts. The first is a set of working allowances that the Central Public Works Department (CPWD) writes into its own rate analysis and contracts. The second is a method: start from the net quantity on the drawing, add the allowance once, and check the site against it.
This guide covers both, material by material. There are no rupee figures here. Rates change every year. The allowances below come from CPWD’s published documents, and the method does not change at all.
What is the standard wastage percentage of construction materials?
The closest thing India has to a standard list is the quantity lines in CPWD’s Delhi Analysis of Rates (2014, Volume 1). Each item there is costed for a fixed amount of finished work, and where a material is lost in cutting, dressing or breakage, the analysis adds a line such as “Add for wastage and breakage @ 2.5%”. The table collects those lines.
| Material and work | Wastage added in the CPWD analysis | Item in the analysis |
|---|---|---|
| Steel bars for RCC (mild steel, deformed, TMT) | 5% (1.05 quintal bought per quintal fixed) | 5.22.1, 5.22.4, 5.22.6 |
| Ceramic glazed wall and floor tiles | 2.5% wastage and breakage | 11.36, 11.37 |
| Vitrified floor tiles, 500 to 1,000 mm | 2.5% wastage and breakage | 11.41 |
| Marble or granite slabs for counters and sills | 5% | 8.2 |
| Fine dressed stone flooring, 40 mm | 10% | 11.28 |
| Brick edging to plinth protection | 10% | 6.44 |
| Plywood and particle board panels in door shutters | 10% | 9.7.3, 9.7.5 |
| Glass panes in steel windows | 10% | 10.30 |
| Marble flooring, 18 mm | 15% | 11.23 |
| Kota stone flooring | 15% (11.5 m² of slab for 10 m² of floor) | 11.26 |
| Marble veneer on walls | 20% | 8.11 |
| Sandstone wall lining, machine-cut edges | 33.3% | 7.23 |
| Cement, sand and aggregate in mortar and concrete | No separate wastage line; quantities come from fixed constants | 3.1 onward, 4.1 onward |
Read the last row carefully, because it covers the materials that cost the most. CPWD does not add a wastage percentage to cement, sand or aggregate inside a concrete or mortar item. It controls them a different way, with a permitted variation in the contract, explained further down.
Paint is not in the table either. Its quantity comes from the coverage per litre, which is worked out in the paint quantity calculation.
Is there an IS code for wastage of materials?
Not as a table of percentages. The Indian Standard people usually mean is IS 10067 : 1982, Material constants in building works. Its scope, clause 1.1, says it covers material constants “excluding wastages”. Note 2 under the scope explains why: wastage varies with region, source, type of material, season and the way material is issued and used, so the user’s department has to assess it.
That makes IS 10067 a net-quantity standard. When it says one cubic metre of brickwork with traditional bricks and 1 cm joints takes 473 bricks (Table 3), or 517 modular bricks (Table 4), that is the count laid in the wall. Anything broken in the truck or cut into bats on site comes on top.
The same standard also records two effects that look like wastage but are not. Concrete made with fine sand uses up to 2.5 per cent more material than concrete made with coarse sand (clause 2.2.1). And the concrete constants go up by 5 per cent for leaner mixes and 7 per cent for richer mixes when crushed aggregate is used instead of shingle (note to Table 2). Both are real consumption. Allow for them by picking the right constant, not by raising the wastage figure.
How much steel wastage is allowed in construction?
Two different figures are in use, and they answer two different questions.
3 per cent, for reconciling steel. Clause 42 of CPWD’s General Conditions of Contract (2014 edition) sets the theoretical quantity of reinforcement and structural steel as the design quantity, including authorised laps and chairs, plus 3 per cent wastage for cutting into pieces. This applies when the department issues the steel. Schedule F then allows a variation of 2 per cent either way over that theoretical figure, checked for each diameter, section and category on its own.
5 per cent, for pricing steel. The rate analysis buys 1.05 quintal of bars for every quintal fixed in the work. It is a costing allowance inside the rate per kilogram.
What the contractor is paid for is net. CPWD Specifications 2009 (Volume 1, clause 5.3.4) measure reinforcement as actually used, not more than the drawing shows, and say wastage and unauthorised overlaps “shall not be paid for”. Binding wire is not measured either; its cost sits inside the rate for reinforcement.
So steel waste costs you twice if it runs high: you bought the extra bars, and nobody pays you for them. A careful bar bending schedule is the tool that keeps it near the allowance, because it plans every cut length against the stock length before the first bar is cut.
How much cement wastage is allowed?
In CPWD contracts there is no cement wastage percentage at all. The theoretical cement for each item comes from the constants in the schedule of rates, and Schedule F of the 2014 contract allows a variation over that figure of:
| Material | Variation allowed over the theoretical quantity |
|---|---|
| Cement, works put to tender at up to ₹5 lakh | 3% plus or minus |
| Cement, works put to tender above ₹5 lakh | 2% plus or minus |
| Bitumen, all works | 2.5% plus only, nil on the minus side |
| Steel reinforcement and structural sections | 2% plus or minus, per diameter, section and category |
| All other materials | Nil |
The ₹5 lakh line is a contract threshold from the 2014 edition, not a price. Bitumen is the only material with a one-way allowance: nothing is allowed on the minus side, so laying less bitumen than the theoretical quantity falls outside the allowance.
The 2 per cent figure for cement sits beside a separate rule in IS 456 : 2000. Clause 10.2.2 asks for measuring equipment accurate to within 2 per cent of the cement and 3 per cent of the aggregate, admixture and water. The two rules do different jobs, but they point the same way: cement is meant to be measured, not guessed.
The everyday version of this, for a house, is in how to calculate building materials, which keeps the cement allowance small for the same reason.
Why do tiles and stone carry such different allowances?
Because the waste comes from cutting, and the amount you cut depends on how the material arrives.
Factory tiles come in fixed, true sizes, so most of a room is laid in whole tiles and the waste is the strip along the walls plus some breakage. That is why the CPWD figure is only 2.5 per cent. In a single small room with big tiles it can be far more, because the last row may need a cut from almost every tile. The tile quantity calculation counts that room by room with the half-tile rule, which is a better way to order tiles for one house than any flat percentage.
Natural stone arrives in uneven slabs and blocks. Kota stone and marble flooring are cut to size on site, so the analysis buys 15 per cent more slab than the floor area. Veneer on a wall needs matched, thin, clean pieces, so marble veneer carries 20 per cent. Sandstone lining is dressed from rough blocks, and the analysis adds a third (33.3 per cent) to the finished stone volume to cover what is cut away. Put the other way round, about a quarter of the block bought ends up as chips.
Where does each material get wasted on site?
Knowing where the loss happens is more useful than the percentage, because that is where you can stop it.
| Material | Where the loss happens | What cuts it |
|---|---|---|
| Steel bars | Offcuts left when cut lengths do not divide the stock length; extra laps | Bar bending schedule; plan laps at the drawing; store bars by diameter and length |
| Cement | Torn bags, spillage at the mixer, bags that set in damp storage, overdosing by the head pan | Dry, raised storage; first-in first-out use; weigh-batching |
| Sand | Material left in the ground under the heap, washed off in rain, bought damp and bulked | Hard standing for the stockpile; check bulking before batching by volume |
| Coarse aggregate | Spread into the ground at the dump, mixed with soil | Dump on a hard base; separate stockpiles by size |
| Bricks | Breakage while unloading by tipping, bats cut at corners and openings | Unload by hand or on pallets; plan openings to brick sizes |
| Tiles | Cuts at walls and around pipes, breakage in handling | Set out the room before laying; keep boxes flat and dry |
| Stone slabs | Trimming to size, edge chipping, slabs rejected for shade | Sort slabs for shade before cutting; cut with a wet saw |
| Concrete | Leftover batch at the end of a pour, leakage from formwork | Order or batch the last load to the measured balance; tight formwork |
Sand bulking deserves a word. Damp sand takes up more room than dry sand, so a box of damp sand holds less sand than it seems. IS 456 clause 10.2.4 requires an allowance for bulking whenever concrete is batched by volume, and the unit weight of building materials page shows how the bulking test works. That is a measuring error, not wastage, but it shows up on site as “we ran out of sand”.
How do you add wastage to a quantity estimate?
Add it to the quantity, once, and never to the rate as well.
Ordered quantity = net quantity from the drawing × (1 + wastage % ÷ 100)
Three worked examples, using the figures above:
- Steel, reconciled the CPWD way. The 10 mm bars in a slab come to 1,000 kg net, laps and chairs included. Add 3 per cent for cutting: the theoretical quantity is 1,030 kg. With the 2 per cent variation, any issue from 1,009.4 kg to 1,050.6 kg reconciles.
- Vitrified tiles. A 40 m² floor in 600 × 600 mm tiles needs 40 × 1.025 = 41 m². One tile covers 0.36 m², so that is 114 tiles, against 112 without the allowance.
- Kota stone. A 10 m² floor needs 11.5 m² of slab at 15 per cent.
What the numbers in Figure 1 show
- Net quantity: what the drawing needs, as IS 10067 constants or a take-off give it. Laps and chairs that the design calls for are part of it.
- Wastage allowance: added once, as a percentage of the net quantity, for cutting, dressing and breakage.
- Theoretical quantity: the figure the material issued should match.
- Variation band: the plus or minus the contract allows around the theoretical figure. Material used beyond it is recovered from the contractor.
Two traps catch most estimates. The first is counting wastage twice. The plaster quantity calculation shows how some sites raise the dry-volume factor to cover spill and then add a wastage percentage on top. Pick one. The second is putting the allowance on the rate as well as the quantity. In a construction estimate format the wastage belongs in the quantity column, or inside the rate analysis, never both.
For a whole house, the quantities and the allowances flow into the house construction cost calculator.
Does weigh-batching reduce cement and aggregate wastage?
It makes the loss visible, which is the first step to cutting it. IS 456 clause 10.2 asks for cement and aggregate to be batched by mass, and allows volume batching only where weighing is not practical. A head pan of cement is a guess; a weighed batch is a number you can set against the theoretical consumption at the end of every day.
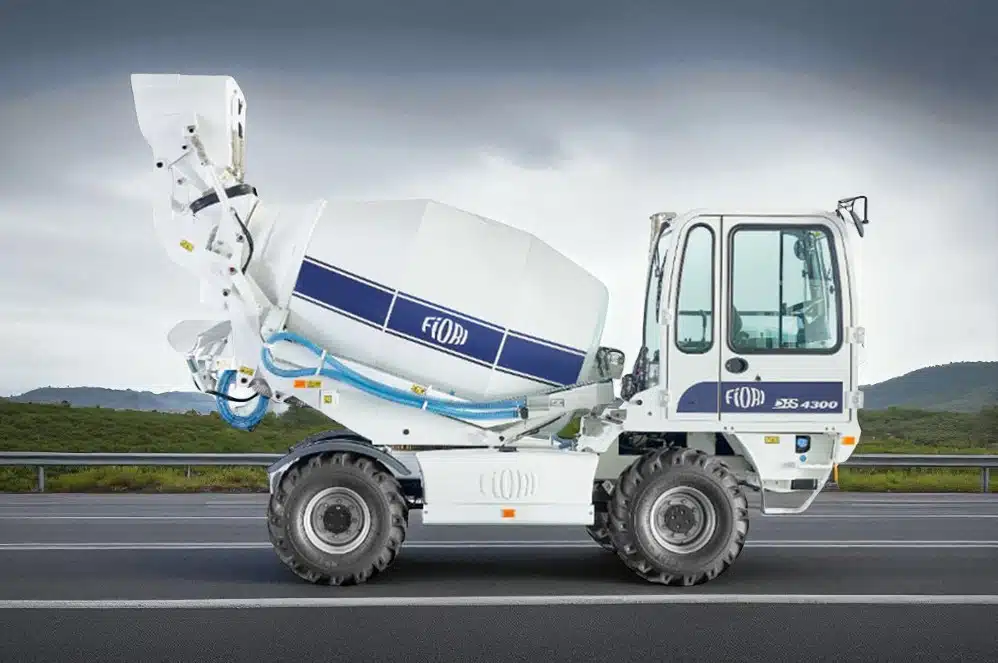
Several self-loading concrete mixers weigh each batch as they load it. The Apollo Carmix 30 FX (3.0 m³ drum) lists a load-cell weighing system. The AJAX ARGO 4500 (4.5 m³ drum) lists a pressure transducer and load cell. The Fiori DBS 4300 (4.3 m³ drum) lists computerised batching with printed certificates, which gives you a record of every batch for the cement reconciliation.
On a bigger job the same logic points to ready-mixed concrete or a batching plant, which IS 456 prefers for large and medium sites. The trade-offs are set out in RMC vs site mix concrete.
To batch your own concrete by weight, compare concrete mixer models and connect with a dealer near you.
Who decides the wastage figure on your job?
On a government contract, the contract does. CPWD’s 2014 conditions say that, unless stated otherwise, the item descriptions in the schedule of quantities include wastage on materials, so the contractor’s rate already carries it, and clause 42 sets the theoretical quantities for any material the department issues. Other departments set their own figures in their own contracts, which is the job IS 10067 leaves to them.
On a private house, you and your contractor do, and it is worth writing down before work starts. Under a labour-only contract the material wastage is your cost; under a turnkey contract it is the contractor’s, as the house cost calculator explains. Either way, a figure agreed in writing, per material, settles the argument that otherwise comes at the final bill.
When you are ready to plan the machines for the concrete work, compare live concrete mixer models and prices and connect with a dealer. More estimating guides sit under construction cost, and the materials themselves under building materials.
Prices, specifications and features are indicative, vary by variant, location and date, and should always be confirmed with the official OEM or authorised dealer before any purchase decision. DesiMachines is not liable for decisions taken on the basis of information that may have changed after publication.
Sources: IS 10067 : 1982 (material constants in building works), clause 1.1 and its Note 2, clause 2.2.1, the note to Table 2, Table 3 and Table 4; CPWD General Conditions of Contract 2014, general rule 6, clause 42 and Schedule F; CPWD Delhi Analysis of Rates 2014, Volume 1, items 5.22, 6.44, 7.23, 8.2, 8.11, 9.7, 10.30, 11.23, 11.26, 11.28, 11.36, 11.37 and 11.41; CPWD Specifications 2009, Volume 1, clause 5.3.4; IS 456 : 2000, clauses 10.2, 10.2.2 and 10.2.4. Mixer weighing systems and drum capacities are from each machine’s own specification sheet as listed in October 2026. The worked examples are illustrations; your drawing and your contract decide the final quantity.
Machines, tenders and news for this industry: Building Construction