 Excavator
294 models
 Backhoe Loader
51 models
 Crane
68 models
 Concrete Mixer
79 models
 Wheel Loader
54 models
 Compactor / Roller
45 models
 Motor Grader
42 models
 Dozer
41 models
 Concrete Pump
66 models
 Skid Steer Loader
11 models
 Telehandler
13 models


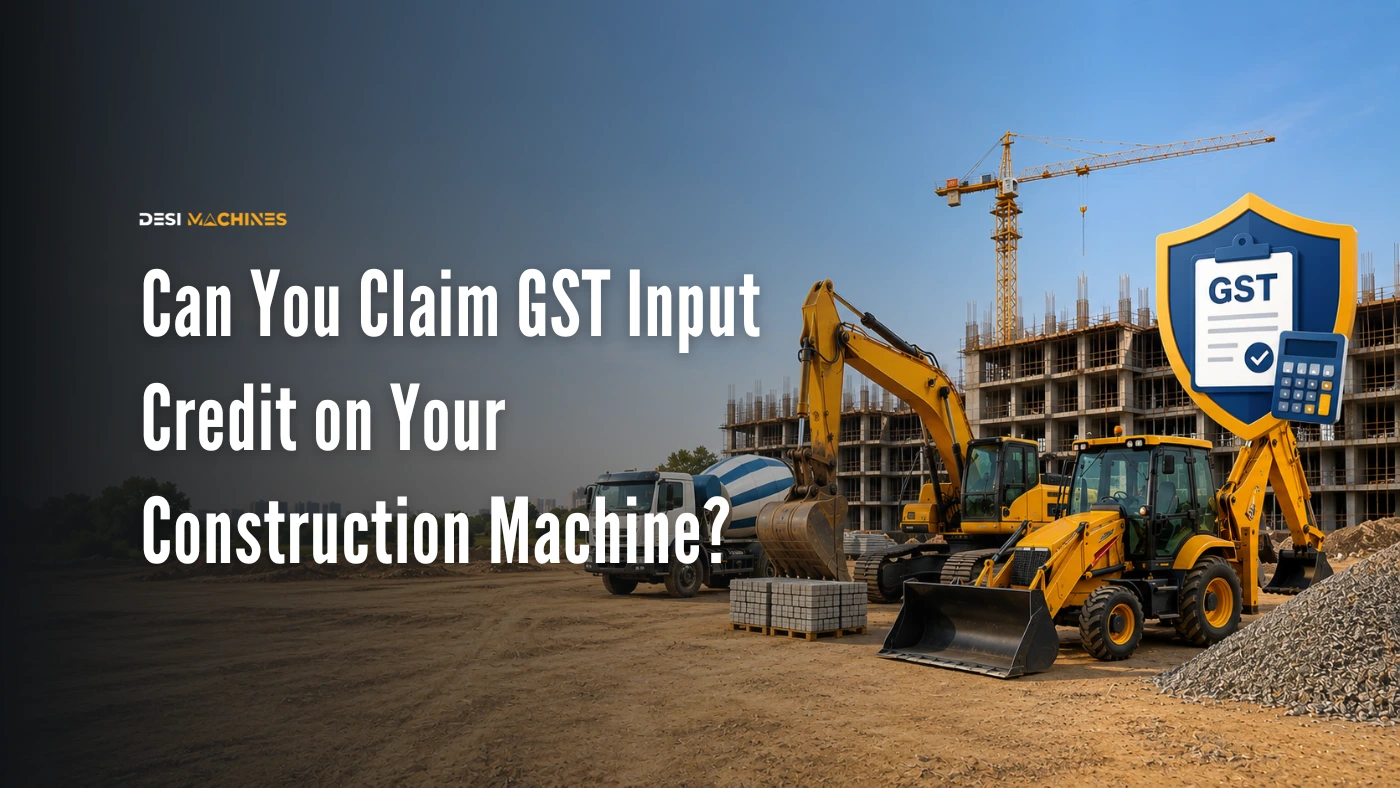
If you run a GST-registered business, you can usually claim GST input credit on construction equipment: an excavator, backhoe loader or wheel loader bought to earn taxable income. The machine counts as plant and machinery, not a passenger vehicle, so the credit is allowed. On an 18% GST (as of October 2026) machine costing ₹28 Lakh before tax (indicative), that is roughly ₹5 Lakh of input tax credit you can set off against your output GST. That is real money, provided the invoice and returns are clean.
Most owners think of GST as just a line that pushes the on-road price up. For a business buyer it is the opposite: that GST is money you can get back. The credit also has a tail: claiming it on the way in is what triggers a payment when you eventually sell the machine, worked through in GST on sale of old machinery. The catch is that “getting it back” depends on a few conditions, and a couple of blocking clauses in the law scare people off machines they were actually entitled to claim on. Let us clear that up.
Who can claim, and on what
Input tax credit (ITC) is the mechanism that stops the same tax being paid twice down a supply chain. You pay GST when you buy the machine (input tax); you charge GST when you bill your customer for earthwork, hire or a works contract (output tax); ITC lets you subtract the first from the second and pay the government only the difference.
Three things have to be true for the credit on a machine to hold:
| Condition | What it means in practice |
|---|---|
| You are GST-registered | The invoice is in your registered business name and GSTIN. A person without registration cannot take credit. |
| Used for business, taxable supply | The machine earns you taxable revenue: earthmoving, site work, rental, a works contract. Not personal use, not a purely exempt activity. |
| Valid invoice, machine received | A proper tax invoice showing GST separately, the machine actually delivered, and the invoice showing up in your GSTR-2B. |
Meet those and the credit is yours. A first machine and the working capital around it are covered in more depth in how much capital you need for your first machine, and the GST set-off is one of the reasons the real cash outgo is lower than the sticker figure suggests.
The two clauses that scare people, and why they usually do not apply
The confusion around gst input credit on construction equipment comes almost entirely from Section 17(5) of the CGST Act, the list of “blocked credits”. Two clauses get quoted at owners:
17(5)(a): motor vehicles. Credit is blocked on motor vehicles for transport of persons with approved seating capacity up to 13. This is the clause that stops you claiming ITC on the office car. An excavator, backhoe loader or wheel loader is not a passenger vehicle. It exists to move earth and material, not people, so this block does not touch it when the machine is used for your business.
17(5)(c) and (d): construction of immovable property. Credit is blocked on goods and services used to build immovable property “on your own account”. Your excavator is not immovable property at all. It is a movable capital good, so these clauses never reach it, and buying the machine is fine. The block only bites if, say, you pour a permanent concrete workshop for your own yard.
The carve-out for plant and machinery in clauses (c) and (d) matters for a different kind of kit. The Explanation to section 17 defines plant and machinery as apparatus, equipment and machinery fixed to earth by a foundation or structural support and used to make taxable supplies, and it includes that foundation. It excludes land, buildings and other civil structures. A concrete batching plant or a stone crusher set on its own foundation fits the definition, so the credit on the plant and on its foundation survives. The shed built over it does not. The Finance Act, 2025 (section 124) changed “plant or machinery” to “plant and machinery” in clause (d) with effect from 1 July 2017, closing the route the Supreme Court had opened in Safari Retreats in October 2024, where it held that a building could qualify as a plant on its facts. The definition and the amendment note are both in the CGST Act as consolidated to 26 May 2025, the Maharashtra GST department’s copy.
Building materials follow the same line. Cement, steel and bricks bought to build your own office, yard or workshop are blocked by clause (d), because that is construction on your own account. The same materials bought to build for a client under a works contract are not on your own account, and clause (c) lets a works contractor take credit on a sub-contracted works contract used to supply the onward one.
The short version: for a machine bought to run a business, Section 17(5) generally leaves the credit intact. It was written to stop people claiming on cars and on their own buildings, not on working plant.
When the credit is genuinely blocked or reduced
ITC is not automatic in every case. Watch these:
| Situation | ITC position |
|---|---|
| Machine used only for exempt supplies | Blocked: no output GST, so no credit to set off. |
| Machine part business, part personal | Only the business-use share is creditable; the personal share is reversed. |
| Bought before you registered for GST | Generally no credit for the period before registration. |
| Invoice not in GSTR-2B / supplier did not pay | Credit held up until it reflects; can be reversed with interest. |
| Dealer not paid within 180 days of the invoice | Pay the credit back with interest; take it again once you pay. |
| Credit claimed after 30 November following the financial year | Time-barred under section 16(4), or earlier if the annual return is filed first. |
| Depreciation claimed on the GST portion under Income Tax | If you capitalise the GST and claim depreciation on it, you cannot also take it as ITC. Pick one. |
That last row trips up a lot of first-time buyers filing their own returns. You either take the GST, about ₹5 Lakh on a ₹28 Lakh machine, as input credit or add it to the machine’s cost and depreciate it, never both. Section 16(3) is the rule, and the income-tax rates you would depreciate at are set out in depreciation rate on construction machinery.
What the credit is actually worth
The 18% is not a small line. On typical machine prices, the credit you can recover looks like this (all figures indicative, GST at 18% as of October 2026):
| Machine | Indicative price (ex-GST) | GST @ 18% = your ITC | Catalogue example (listed, October 2026) |
|---|---|---|---|
| Backhoe loader (e.g. JCB 3DX class) | ₹28–34 Lakh | ₹5.0–6.1 Lakh | JCB 3DX, ₹30–32 Lakh |
| Mini / small excavator | ₹22–30 Lakh | ₹4.0–5.4 Lakh | JCB 30 Plus, ₹26–28 Lakh |
| 20-tonne excavator | ₹51–80 Lakh | ₹9.2–14.4 Lakh | Tata Hitachi EX 210 Infra, ₹60–65 Lakh |
For a contractor billing GST on site work, that credit comes back through the returns over the following months as you set it off against output tax. It changes the true cost of the machine, and it is worth building into the numbers before you sign, the same way the full cost of ownership of an excavator should sit in the decision, not just the EMI. Listed prices on model pages are indicative, so ask the dealer whether a quote is before or after GST: the credit is 18% of the pre-tax value. The materials on that same job carry their own rates, set out in GST on building materials with HSN codes.
Keep the paperwork clean from day one
Most ITC problems are documentation problems, not eligibility problems. Before you take delivery:
Get the tax invoice in your exact registered name and GSTIN, with the GST shown as a separate line, not buried in a lump sum. Check within a month that the invoice appears in your GSTR-2B. If the dealer has not filed, your credit waits. Claim it in the right GSTR-3B period and keep the invoice, delivery challan and payment proof filed together. If you are funding the machine, the loan is a separate track entirely; see construction equipment loan eligibility for that side and arrange your equipment finance in parallel.
Two clocks run once the machine arrives. If you have not paid the dealer the value and the tax within 180 days of the invoice date, the second proviso to section 16(2) makes you pay back the credit with interest, and you take it again when you pay. A loan paid straight to the dealer clears that test on day one; dealer credit and part-payments are where it bites. And section 16(4) closes the door on any invoice after 30 November following the end of the financial year, or the date you file the annual return if that comes first. An invoice found missing only while preparing the December GSTR-9 annual return is usually already out of time.
For the exact GST rate and HSN classification of your specific machine, and how it feeds the on-road price, read the tax rate breakdown for construction equipment before you rely on any single figure here.
Who can claim GST input credit on construction equipment?
If you are GST-registered and the machine earns you taxable income, you can almost always claim gst input credit on construction equipment. The motor-vehicle and immovable-property blocks in Section 17(5) were not written for working plant. The credit is real money, often ₹4–14 Lakh, but it lives or dies on a clean invoice, a GSTR-2B match, paying the dealer inside 180 days, and not double-dipping with depreciation. Get the paperwork right at purchase and treat the GST as recoverable, not sunk.
Planning the buy? Compare live prices across the excavator and backhoe loader ranges, line up your numbers on the equipment finance side, weigh the funding routes in loan vs lease vs cash, and talk to your CA about your specific ITC position before you file. The credit is worth the ten minutes it takes to check.
Tax rules, GST rates, HSN classification and prices are indicative, apply to the position as of October 2026, and change with law and notification. Section 17(5) treatment depends on your exact facts. Confirm your own eligibility with your CA or a qualified tax advisor, and the current rate and terms with the OEM, dealer or bank, before deciding. DesiMachines is not liable for decisions taken on information that may have changed after publication.